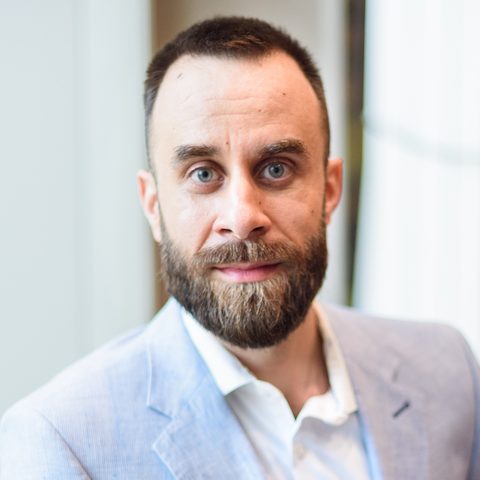
Dimitrije Ruzic is Associate Professor of Economics at INSEAD and Research Affiliate at the Centre for Economic Policy Research (CEPR).
His research spans macroeconomics and international trade. He works to understand how differences across firms shape macroeconomic outcomes. His recent work has appeared in the Journal of Political Economy, the Journal of Economic Literature, the Review of Economics and Statistics, and the Journal of the European Economic Association.
At INSEAD he teaches macroeconomics to MBA, Executive MBA, and executive education participants. For his efforts to make the global economic environment accessible to diverse audiences, he was named among the Best 40-Under-40 MBA Professors by Poets & Quants and among 30 emerging thinkers to watch by Thinkers50. INSEAD MBA students have voted him Best Teacher of a core course, and he has been awarded the Dean’s Commendation for Excellence in MBA Teaching multiple times.
He holds economics degrees from Harvard, the London School of Economics, and the University of Michigan. If you cannot find him in his office, please look around the Fontainebleau forest—he might be bouldering.
Research
Working Papers and Work in Progress
-
Establishments vs Firms: Wage Setting and the (Mis)Allocation of Labor
-
Implications of the Transatlantic Productivity Gap for EU and US Living StandardsIn preparation for the Brookings Papers on Economic Activity
Publications and Accepted Papers
-
Superstars or Supervillains? Large Firms in the South Korean Growth MiracleJournal of Political EconomyWorking PaperNBERCEPR
Abstract
We quantify the contribution of the largest firms to South Korea's economic performance over the period 1972-2011. Using firm-level historical data, we document a novel fact: firm concentration rose substantially during the growth miracle period. To understand whether rising concentration contributed positively or negatively to South Korean real income, we build a quantitative dynamic heterogeneous-firm small-open-economy model. Our framework accommodates a variety of potential causes and consequences of changing firm concentration: productivity, distortions, selection into exporting, scale economies, and oligopolistic and oligopsonistic market power in domestic goods and labor markets. The model is implemented directly on the firm-level data and inverted to recover the drivers of concentration. We find that most of the differential performance of the top firms is attributable to higher productivity growth rather than increasingly favorable distortions. Exceptional performance of the top 3 firms within each sector relative to the average firms contributed 21.8% to the 2011 real GDP and 6.9% to the net present value of welfare over the period 1972-2011. Thus, the largest Korean firms were superstars rather than supervillains.
-
Micro and Macro Perspectives on Production-Based MarkupsJournal of Economic LiteratureWorking PaperCEPR
Abstract
We review the "production approach" to estimating markups, the ratio of price to marginal cost. The approach is scalable. It requires no model of consumer demand or market structure and applies broadly across firms, industries, and time. We organize our review around a simple insight: the production-based markup is a residual. Like the Solow residual, it is clean in theory but potentially contaminated by misspecification and mismeasurement. This framing helps explain why small differences in implementation can produce starkly different results from the same data. In some cases, estimated markups have risen sharply. In others, they have not. We provide conceptual rationales for these disagreements, offer practical guidance on data and estimation, and call for greater transparency about how much of the variation attributed to markups may instead reflect technology.
-
The Factor Bias of External Inputs: Implications for Substitution between Capital and LaborReview of Economics and StatisticsWorking PaperCEPR
Abstract
This paper reevaluates the longstanding debate on capital-labor substitution by examining the role of external inputs: raw materials, intermediate goods and services, imports, offshoring. Both a meta analysis (analyzing existing estimates of substitution) and direct inference (using U.S. data for 1963-2016) indicate that external inputs disproportionately displace labor. These findings imply (1) that the capital-labor ratio responds 40-80% more strongly to the price of labor than to the price of capital, (2) that value added cannot be modeled separably from gross output, and (3) that historical disagreements regarding substitution can be recast as an omitted variable bias involving external inputs.
-
The Productivity Slowdown in Advanced Economies: Common Shocks or Common Trends?Review of Income and Wealth, 2024Published VersionWorking Paper
Abstract
This paper reviews advanced-economy productivity developments in recent decades. We focus primarily on the facts about, and explanations for, the mid-2000s labor-productivity slowdown in large European countries and the United States. Slower total factor productivity (TFP) growth was the proximate cause of the slowdown. This conclusion is robust to measurement challenges including the role of intangible assets, rankings of productivity levels, and data revisions. We contrast two main narratives for the stagnating TFP frontier: The shock of the Global Financial Crisis; and a common slowdown in TFP trends. Distinguishing these two empirically is hard, but the pre-recession timing of the U.S. slowdown suggests an important role for the common-trend explanation. We also discuss the unusual pattern of labor productivity growth since the start of the Covid-19 pandemic. Although it is early, there is little evidence so far that the large pandemic shock has changed the slow pre-pandemic trajectory of labor-productivity growth.
-
Firms and Collective Reputation: a Study of the Volkswagen Emissions ScandalJournal of the European Economic Association 21(2), 2023Published VersionWorking PaperNBER
Abstract
This paper uses the 2015 Volkswagen (VW) emissions scandal as a natural experiment to provide evidence that collective reputation externalities are economically significant. Using a combination of difference-in-differences and demand estimation approaches, we document a spillover effect from the scandal to the non-VW German auto manufacturers. The spillover amounts to an average drop of $2,057 in consumer valuations of these manufacturers' vehicles and to a 34.6% reduction in their annual sales. We substantiate our interpretation that the estimates reflect a reputation spillover using data on internet search behavior and direct measures of consumer sentiment from Twitter.
-
Returns to Scale, Productivity Measurement, and Trends in U.S. Manufacturing MisallocationReview of Economics and Statistics 105(5), 2023Published VersionWorking Paper
Abstract
Aggregate productivity suffers when workers and machines are not matched with their most productive uses. This paper builds a model that features industry-specific markups, industry-specific returns to scale, and establishment-specific distortions, and uses it to measure the extent of this misallocation in the economy. Applying the model to restricted U.S. census microdata on the manufacturing sector suggests that misallocation declined by 13% between 1982 and 2007. The jointly-estimated markup and returns to scale parameters vary substantially across industries. Furthermore, while the average markup has been relatively constant, the average returns to scale declined over this period. The finding of declining misallocation starkly contrasts the 29% increase implied by the widely used Hsieh & Klenow (2009) model, which assumes that all establishments charge the same markup and have constant returns to scale. Accounting for the variation in markups and returns to scale leads to the divergence of misallocation estimates in this paper from those implied by the Hsieh-Klenow model.
-
Globalization and Top Income SharesJournal of International Economics 125, 2020Published VersionWorking Paper
Abstract
This paper documents empirically that access to global markets is associated with a higher executive-to-worker pay ratio within the firm. It then uses China's 2001 accession to the World Trade Organization as a trade shock to show that firms that exported to China prior to 2001 subsequently exported more, grew larger, and grew more unequal in terms of executive-to-worker pay. To evaluate analytically and quantitatively the impacts of globalization on top income inequality, this paper builds a model with heterogeneous firms, occupational choice, and executive compensation. In the model, executive compensation grows with the size of the firm, while the wage paid to ordinary workers is determined in a country-wide labor market. As a result, the extra profits earned in the foreign markets benefit the executives more than the average workers. We calibrate the model to the U.S. economy and match the income distribution closely in the data. Counterfactual exercises suggest that trade and FDI liberalizations can explain around 44 percent of the surge in top 0.1 percent income shares in the data between 1988 and 2008.
Teaching
INSEAD
- Macroeconomics in the Global Economy (MBA)
- Macroeconomics (Executive MBA)
- Econometrics B (PhD)
- Global Economic Outlook (Executive Education)
Poets & Quants’ Best 40-Under-40 MBA Professors: 2025
Dean’s Commendation for Excellence in MBA Teaching: 2021, 2022, 2025
University of Michigan
- Intermediate Macroeconomics (Undergraduate)
Letter of Commendation for Excellence in Teaching: 2013
Contact
INSEAD
1 Boulevard de Constance
77300 Fontainebleau
France